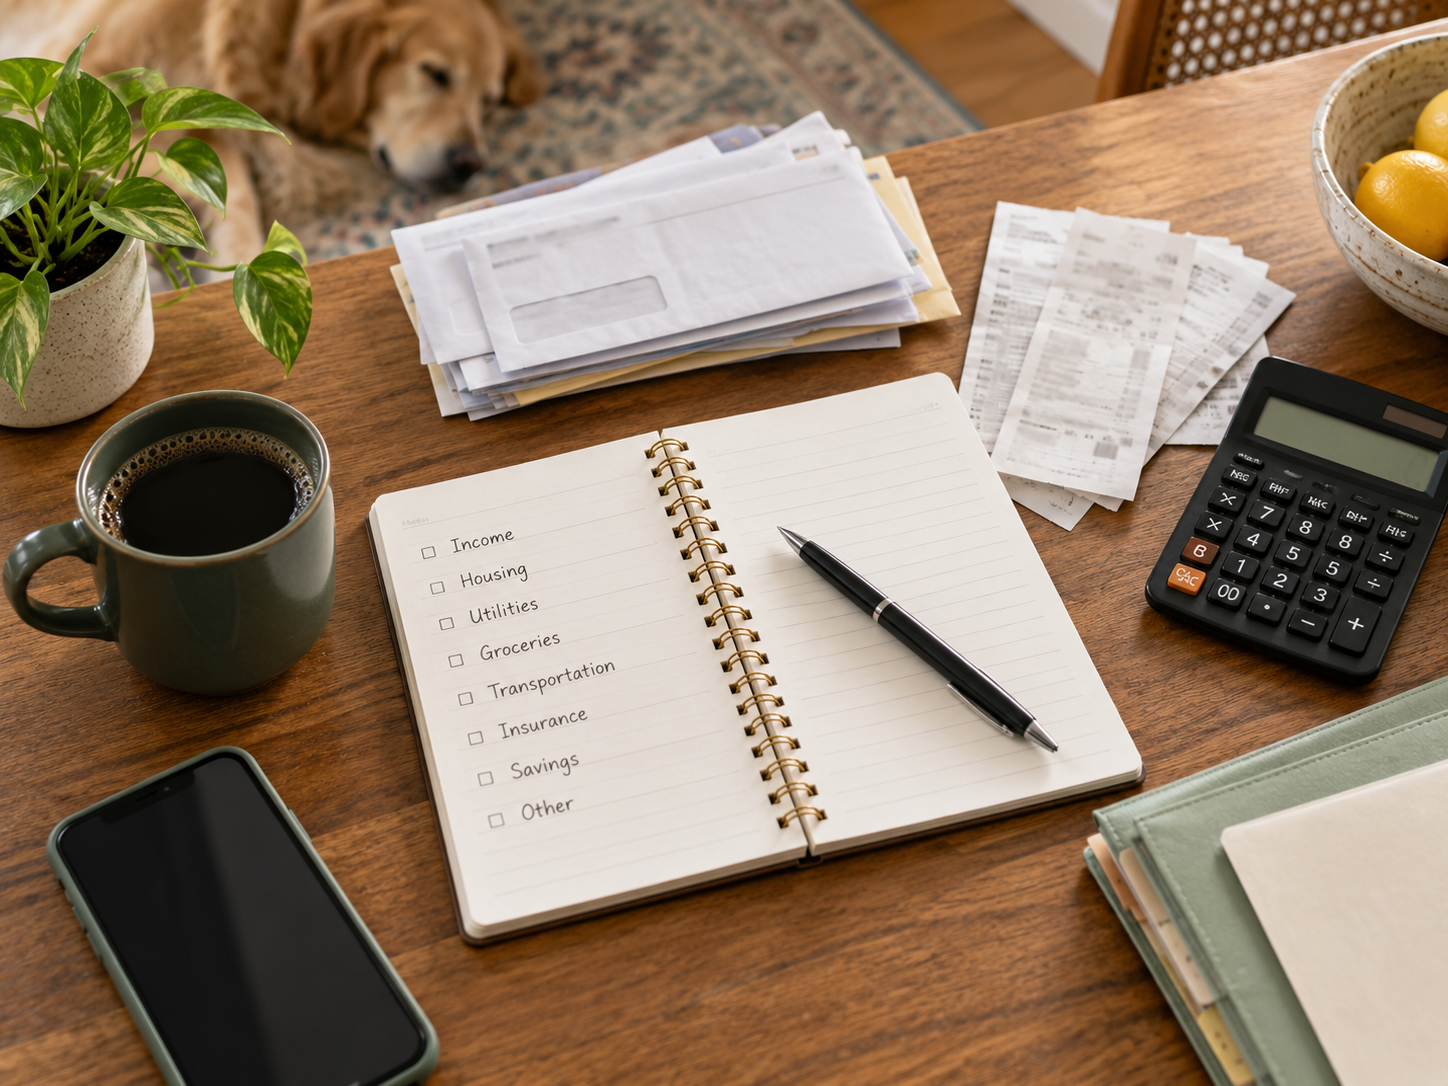
Build a Budget That Actually Works for Your Real Life
A budget should make your money easier to manage—not make you feel like you failed every time real life happens.
Most budgets fail for a simple reason: they are built for an imaginary month.
The imaginary month has no car repairs, birthdays, school costs, medical copays, forgotten subscriptions, seasonal utility spikes, or dinners ordered because everyone is exhausted. A useful budget accounts for real life.
Step 1: Find out what you actually spend
Before deciding what you “should” spend, look at the last two or three months of transactions. Group them into broad categories such as housing, groceries, transportation, utilities, debt, insurance, childcare, subscriptions, dining out, shopping, savings, and miscellaneous spending.
Taja Undated Budget Planner & Expense Tracker
Once you have pulled together a few months of spending, an undated planner can help you organize monthly income, bills, spending, savings, and financial goals in one place instead of scattered across statements.
Paid link
Step 2: Separate fixed and flexible expenses
Fixed expenses stay relatively stable, such as rent or mortgage, insurance, subscriptions, and minimum debt payments. Flexible expenses change month to month: groceries, fuel, entertainment, clothing, and dining out. Flexible categories are usually where adjustments are easiest.
Step 3: Add irregular expenses
Annual insurance premiums, holidays, birthdays, school supplies, vehicle registration, home repairs, travel, and seasonal expenses are predictable even if they do not happen monthly. Estimate the annual amount, divide by 12, and save a little each month.
Step 4: Give savings its own category
Savings should not be whatever happens to remain at the end of the month. Treat it like a bill whenever possible. Separate goals can include an emergency fund, retirement, travel, home repairs, a vehicle, education, or business goals.
SKYDUE Budget Binder with Cash Envelopes
If you like the cash-envelope method, a binder can help separate money for categories such as groceries, personal spending, household expenses, savings, and other flexible parts of your budget.
Paid link
Step 5: Leave room for enjoyment
A budget that allows zero spending on fun is difficult to sustain. Include a realistic amount for eating out, hobbies, entertainment, or personal spending. The plan should reflect the fact that you are a human being, not a spreadsheet.
Step 6: Create a buffer
A small miscellaneous category can absorb forgotten expenses without blowing up the entire plan. Even a modest buffer can make budgeting feel much more forgiving.
Step 7: Decide where extra money goes before it arrives
Bonuses, overtime, tax refunds, gifts, or side-hustle income can disappear quickly without a plan. Create a rule in advance for how much goes to savings, debt, investing, or something enjoyable.
Step 8: Use categories that make sense to you
You do not need thirty categories. If “household” works better than separating toiletries, cleaning supplies, paper goods, and miscellaneous home items, use one category. A budget is a decision-making tool, not an accounting exam.
Step 9: Review weekly instead of panicking monthly
A five-minute weekly check can prevent surprises. Look at upcoming bills, category totals, account balances, and anything unusual. Small corrections are easier than discovering a problem at the end of the month.
Step 10: Adjust when your life changes
Childcare changes. Income changes. Grocery costs rise. Loans get paid off. New goals become important. Your budget should change with you.
A good budget gives you permission to spend
People often think budgeting is about saying no. A well-built budget also tells you when you can safely say yes. If money for dinner out, a hobby, or a weekend trip is already part of the plan, you do not have to feel guilty about spending it.
Frequently Asked Questions
What budgeting method is best?
The best one is the one you will consistently use. Zero-based budgets, percentage budgets, cash envelopes, and simple category budgets can all work.
How often should I update my budget?
Review it briefly each week and make larger changes whenever income, bills, or priorities change.
What if expenses are higher than income?
Start with the largest flexible expenses and recurring bills, then look for ways to increase income. Small cuts alone may not solve a large monthly gap.
Make the plan fit your life
Your budget does not need to look like anyone else’s. Once the framework is in place, 10 Realistic Side Hustles You Can Start From Home can help you grow the income side, and Could Tiny House Living Be Right for You? can help you shrink the expense side.
Affiliate disclosure: This post may contain affiliate links. As an Amazon Associate I earn from qualifying purchases.